Guides & Tips
Bank vs In-House Financing for Cars in the Philippines
By Richard Cuagdan, Mitsubishi Sales Executive ·
Quick answer: Bank vs in-house financing, in short. Bank financing is the common route for brand-new cars and is subject to bank approval, with requirements and terms set by the bank. In-house or other non-bank financing may differ in requirements, speed and total cost. Compare the total amount you'll pay over the term, the inclusions, the requirements and the fees, not just the monthly.
"Bank o in-house?" Both are ways to finance a car, but they're not the same deal. Here's a fair way to compare, so you're choosing based on numbers, not pressure.
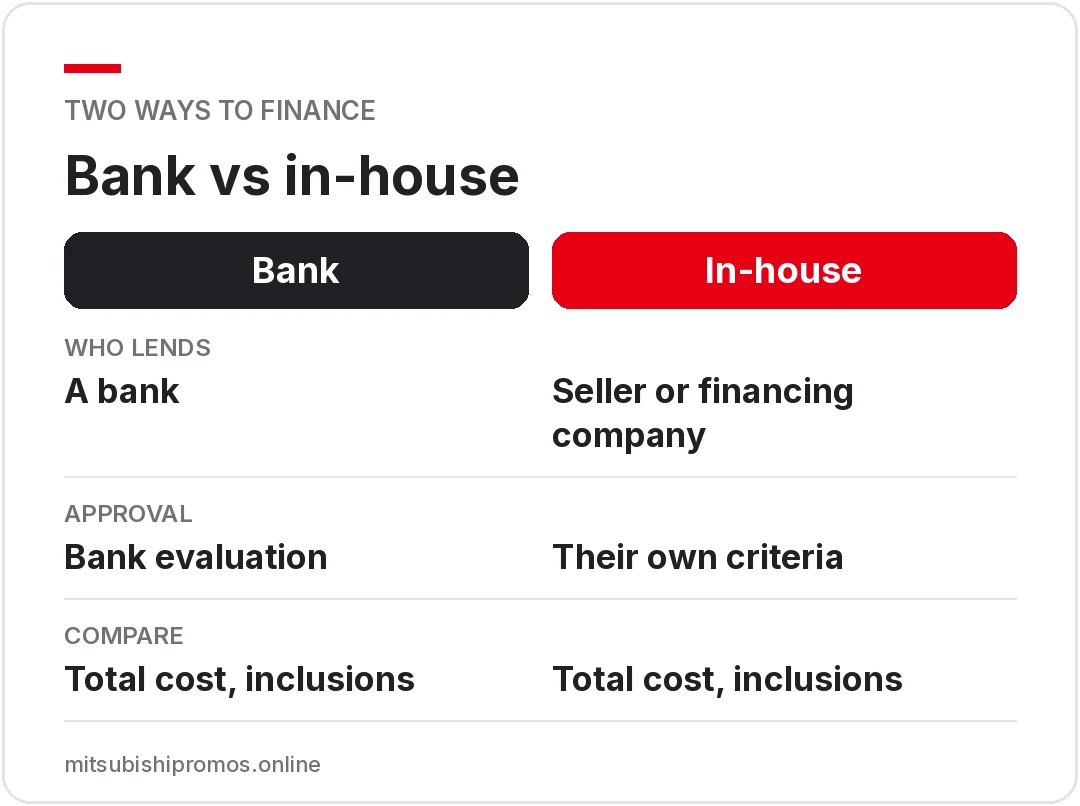
How bank financing works
- A bank pays the dealer; you pay the bank monthly over the term
- Approval depends on the bank's evaluation of your capacity, documents and credit history
- The car is under a chattel mortgage until the loan is paid (included in the all-in package)
- Banks typically require comprehensive insurance while financed
More in my how car financing works guide.
What "in-house" usually means
In-house or non-bank financing is offered by the seller or a financing company rather than a bank. Requirements, approval speed and total cost can differ from a bank loan. Every offer is different, so treat each one on its own terms.
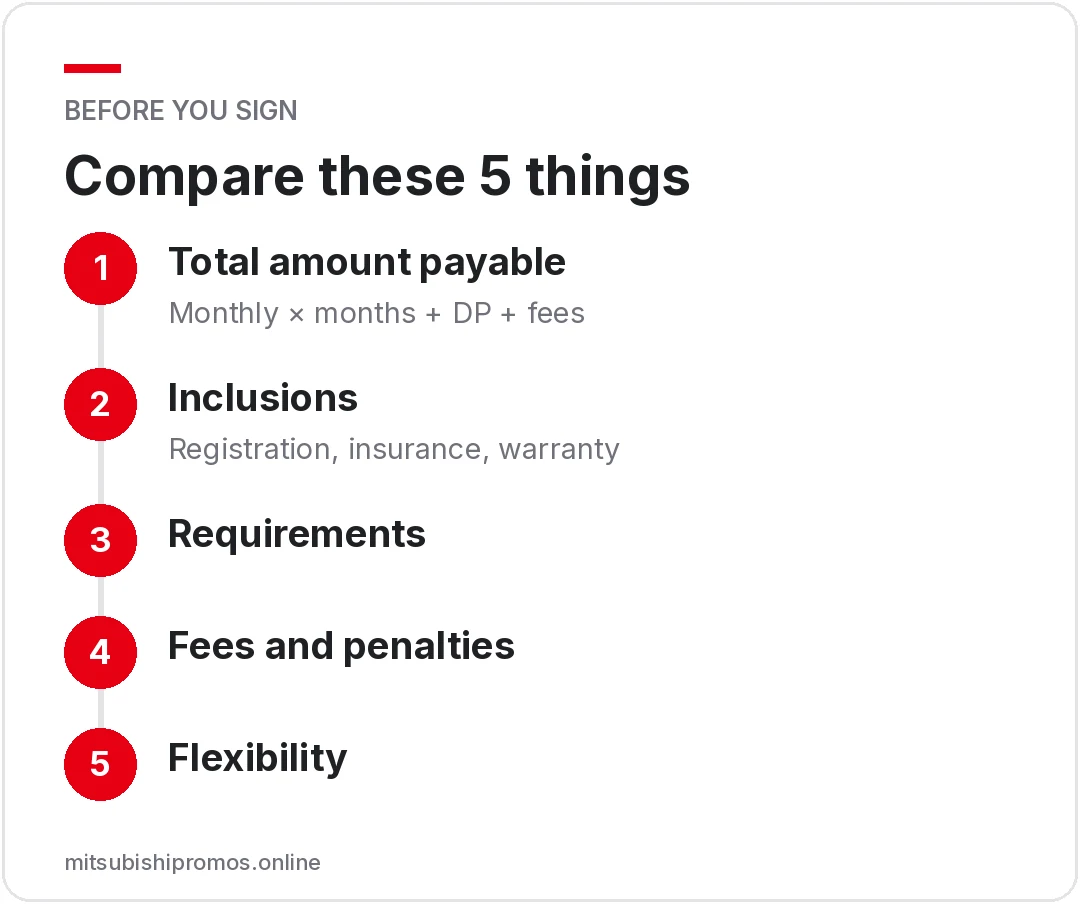
Compare these five things
Total amount payable
Monthly × number of months + down payment + fees. This is the real price.
Inclusions
Registration, insurance, chattel mortgage, warranty. See what all-in includes.
Requirements
What documents and income proof each option needs.
Fees and penalties
Processing fees, late payment penalties, early payoff rules.
Flexibility
Term options and what happens if your situation changes.
A sample: what an all-in promo includes
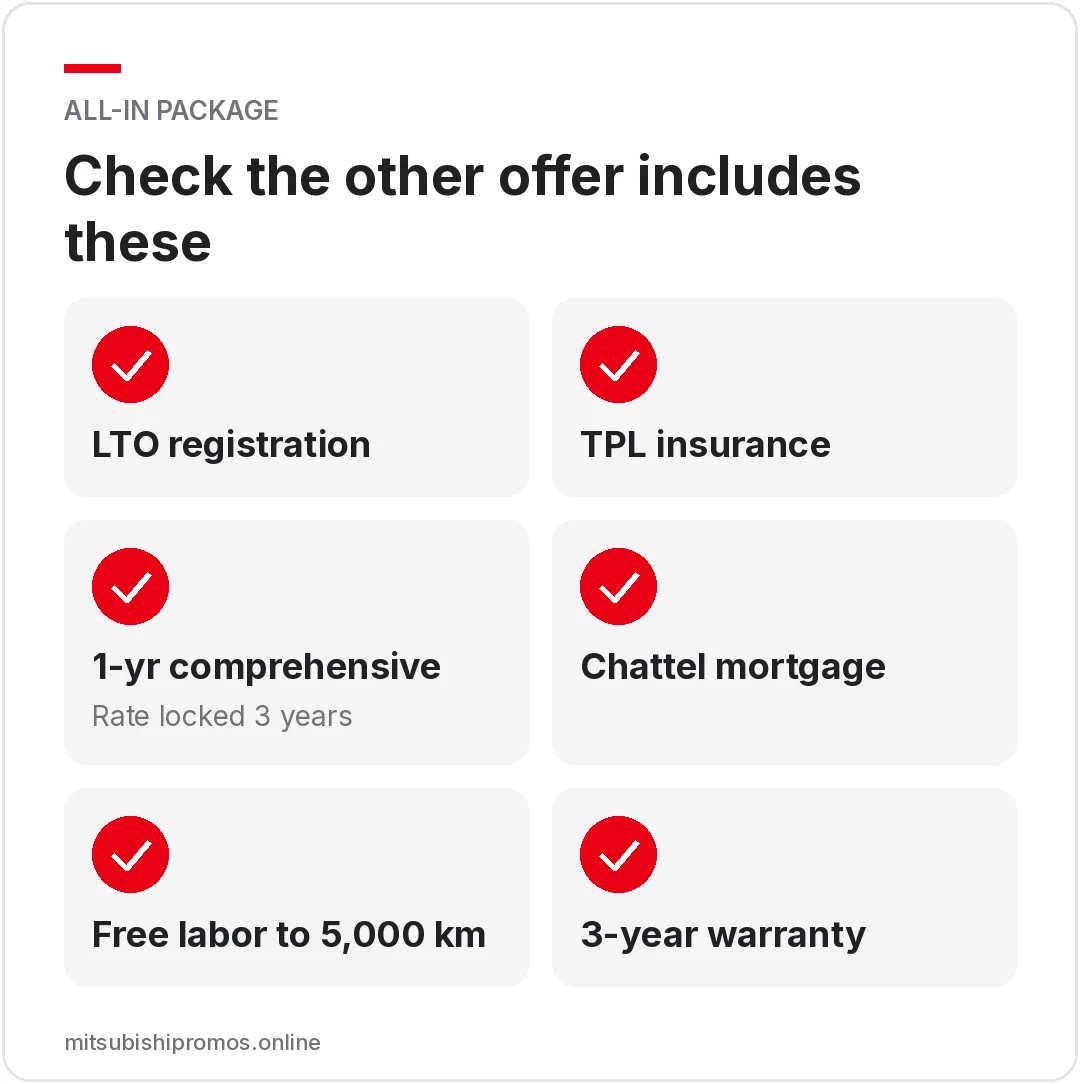
For example, the Xpander GLX AT this month is ₱23,592 a month at ₱23K DP for 60 months, all-in, with 60K fuel. The all-in package covers LTO registration, TPL insurance, 1-year comprehensive insurance with the rate locked for 3 years, chattel mortgage, free labor up to 5,000 km and a 3-year warranty. When comparing offers, check that the other one includes the same items, or add their cost. (October 2026 promo, subject to bank approval.)
Red flags
- No written breakdown of the total cost
- Pressure to sign the same day
- Unclear who holds the car's documents
- Fees that appear only at signing
Not sure you'll be approved? Read car loan myths and prepare with the requirements list.
Related reading
- Paano Bumili ng Bagong Sasakyan: Cash o Financing
- Zero Down Payment Car Philippines: October 2026 List
- First-Time Car Buyer Checklist Philippines (2026)
Your next step
Want a clear, written all-in breakdown? Check your budget, then message me or book a test drive in SJDM.
Check what fits my budget Book a Test Drive Call or text 0954 291 1201
Questions muna? Call or text me, Richard, on 0954 291 1201, walang pressure. Richard Cuagdan, Mitsubishi SJDM, serving SJDM, Bulacan and Quezon City; message me for showroom visits and directions. Promo figures are for October 2026 on a 5-year term, all-in, subject to bank approval and change without notice.
Frequently asked questions
Which is cheaper, bank or in-house financing?
It depends on the offer. Compare the total amount paid over the full term, including fees and inclusions, from each option.
Are this site's promos bank-financed?
Promo monthlies here are all-in packages subject to bank approval. Message me for details of the financing behind your chosen unit.
Is in-house financing easier to get approved?
Requirements can differ, but easier approval may come with different costs or terms. Read everything before signing.
What should I ask before signing any car loan?
Total amount payable, term, what's included, fees and charges, penalties for late payment, and early payoff rules.