Guides & Tips
Minimum Salary for Car Loan: Young Professional Budget Plan
By Richard Cuagdan, Mitsubishi Sales Executive ·
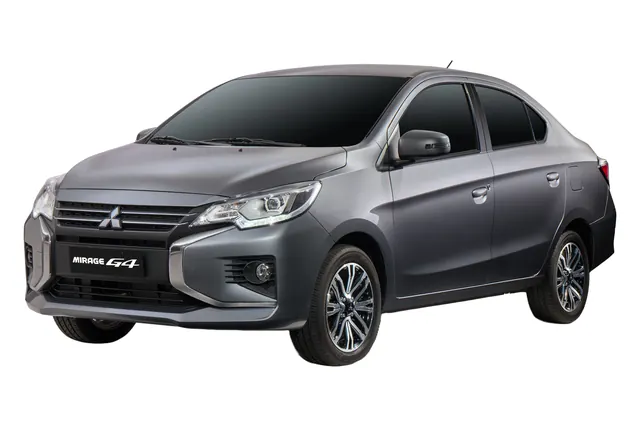
Quick answer: There's no single minimum salary for car loan approval; banks decide, but you can plan. Build an emergency fund first, then keep your car monthly at about 30 to 35 percent of gross income, and budget separately for fuel, parking, tolls, PMS and insurance renewal. Start with a unit that fits comfortably rather than the dream car, and consider a co-borrower or larger down payment if needed.
Unang sahod, unang kotse? It's a big step, and done right, a car makes work and life easier. Done wrong, it eats your sahod every month. Here's a simple plan.
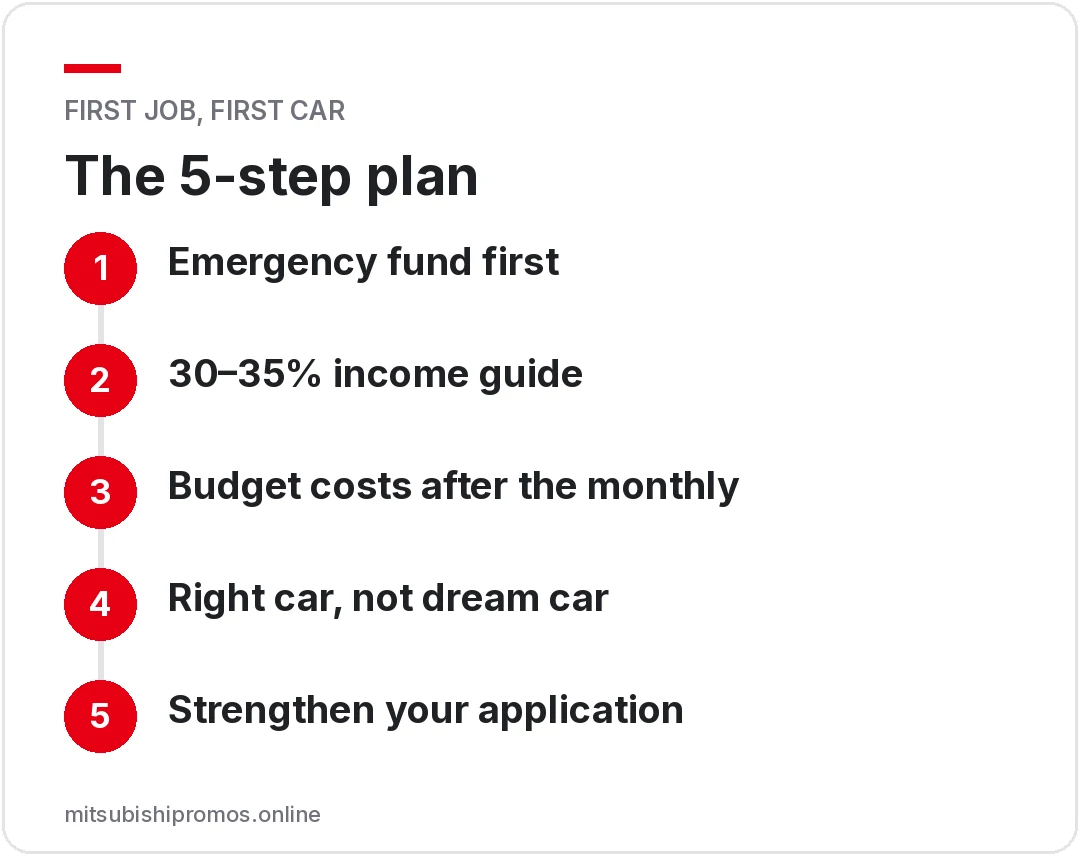
Step 1: Emergency fund first
Before buying, save a few months of expenses. Jobs change, emergencies happen, and the monthly doesn't wait.
Step 2: Use the 30–35% guide
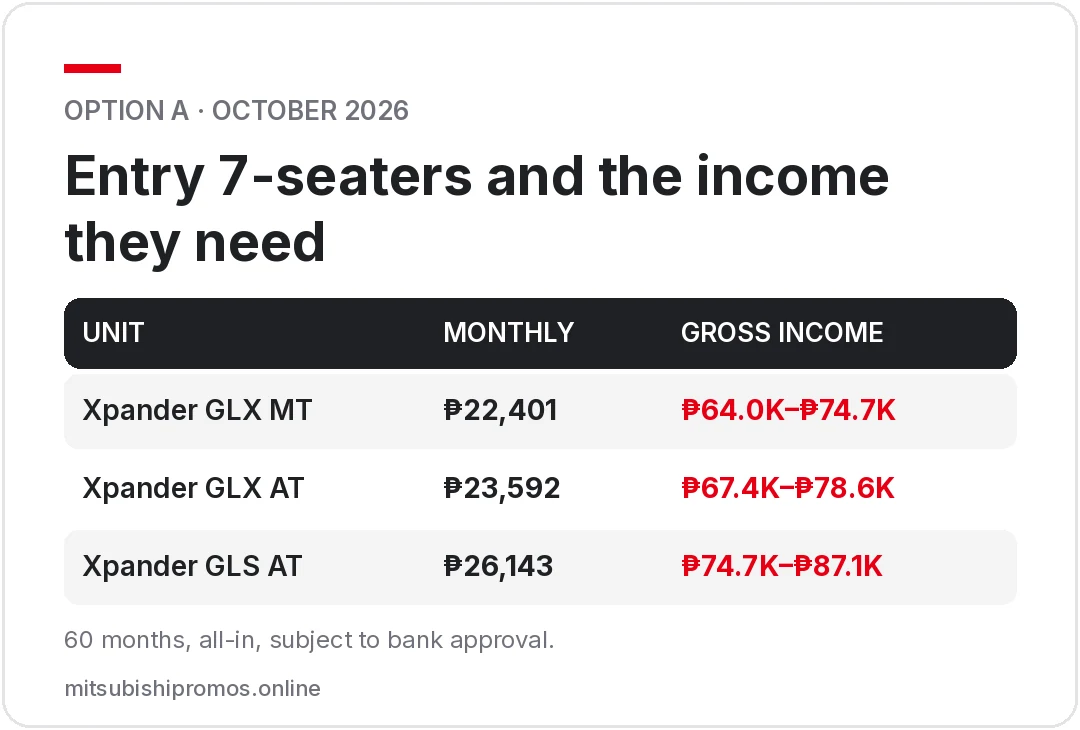
Keep the amortization at about 30 to 35 percent of gross monthly income. Divide the monthly by 0.35 for the minimum income and by 0.30 for a comfortable one. Full table in How much car can I afford?
| Unit (Option A, Oct 2026) | Monthly | Gross income |
|---|---|---|
| Xpander GLX MT | ₱22,401 | ₱64,000 – ₱74,700 |
| Xpander GLX AT | ₱23,592 | ₱67,400 – ₱78,600 |
| Xpander GLS AT | ₱26,143 | ₱74,700 – ₱87,100 |
October 2026 dealer promos, 60 months, all-in. Subject to bank approval and change without notice. Message me for the latest promo.
For a compact sedan like the Mirage G4, message me for the latest promo.
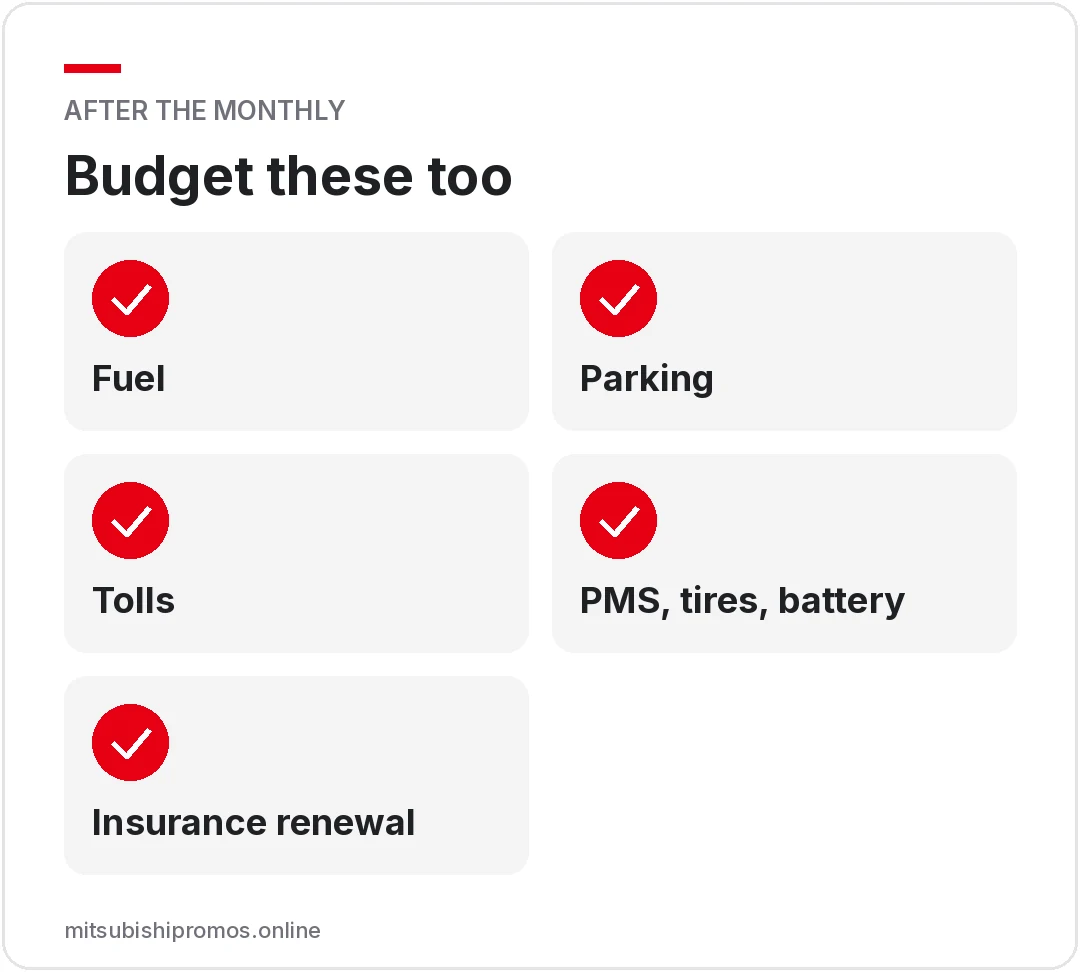
Step 3: Budget the costs after the monthly
- Fuel: estimate weekly kilometers × pump price
- Parking at home, at work, and where you go often
- Tolls if you use expressways
- PMS, tires and battery over time
- Comprehensive insurance renewal after the locked period
Step 4: Pick the right car, not the dream car
- Start with what fits comfortably; you can upgrade later with a trade-in (see trade-in tips)
- Manual can lower the monthly if you're comfortable with it
- Think about who rides with you: barkada, family, carpool
Step 5: Strengthen your application
Complete documents
COE with compensation, payslips, IDs, proof of billing. See the requirements.
Keep credit clean
Pay credit cards on time.
Consider a co-borrower
A parent or spouse, if the bank allows.
Bigger down payment
Lowers the monthly; see Zero DP vs low DP.
Related reading
- 13th Month Pay 2026: A Smart Car Budget Plan
- How to Get Your Car Loan Approved in the Philippines: What Banks Check
See also: the Mirage G4 downpayment and monthly guide.
Your next step
See which unit fits your first-job salary, then book a test drive in SJDM.
Check what fits my budget Book a Test Drive Call or text 0954 291 1201
Questions muna? Call or text me, Richard, on 0954 291 1201, walang pressure. Richard Cuagdan, Mitsubishi SJDM, serving SJDM, Bulacan and Quezon City; message me for showroom visits and directions. Promo figures are for October 2026 on a 5-year term, all-in, subject to bank approval and change without notice.
Frequently asked questions
How much salary do I need to buy a car?
Use the 30–35% guide. For example, the Xpander GLX MT at ₱22,401 a month (₱18K DP, October 2026) fits a gross income of roughly ₱64,000 to ₱74,700. Banks make the final assessment.
Should I save an emergency fund before buying a car?
Yes. A few months of expenses saved protects you if income stops, so the car never becomes a burden.
Is it better to buy a car or keep commuting?
Compare the full monthly cost of owning (amortization plus running costs) with your current commuting costs and the time you'd save.
Can I apply if I'm newly employed?
Banks usually look at length of employment. Ask me what your bank requires; a co-borrower can help.